Owning a dog in America can cost considerably more than the adoption fee, a bag of food, and an occasional trip to the veterinarian.
In 2026, caring for an adult dog costs an estimated $1,930 to $5,305 a year, according to Rover’s latest Cost of Pet Parenthood Report.
That works out to approximately $161 to $442 a month. And we’re talking about a dog you already own, not the initial expenses of bringing a puppy home.
What is interesting about this estimate is the enormous difference between the low and high ends. Two households can both provide responsible care for their dogs and spend thousands of dollars apart each year.
The dog’s size, food, medical needs, insurance coverage, and grooming requirements all influence the bill.
But there’s another important consideration: the expenses that don’t happen every month, yet can completely change what a year of dog ownership costs.
The Annual Cost of Owning an Adult Dog in 2026
Rover’s 2026 dog ownership cost report provides estimated annual expenses for dogs at different stages of life.
For adult dogs, the breakdown covers everything from food and preventative treatments to insurance and replacement supplies.
Here is what those individual expenses look like.
| Expense | Estimated Annual Cost |
|---|---|
| Food | 785–2,635 |
| Treats and chews | 55–360 |
| Gear and supplies | 75–175 |
| Veterinary visits | 80–135 |
| Preventative medications | 295–360 |
| Training sessions | 40–290 |
| Dental hygiene | 55–490 |
| Pet insurance | 520–1,230 |
| Toys | 5–90 |
The table reveals something that is very easy to overlook when calculating the cost of a pet.
Food is a major expense, but keeping a dog healthy and protected can also consume a substantial portion of the budget.
Insurance, parasite prevention, dental care, and veterinary appointments can collectively rival or exceed the cost of feeding a dog, depending on the animal and the owner’s choices.
And these are primarily predictable expenses. An unexpected illness, surgery, or emergency visit is a separate financial consideration.
Dog Food Can Account for More Than $2,600 a Year
Food is one of the largest recurring expenses associated with dog ownership. Rover estimates that feeding an adult dog costs between $785 and $2,635 annually.
That translates to approximately $65 to $220 each month. The range is wide for several reasons.
A small dog naturally needs fewer calories than a large dog. The difference in food consumption between a 12-pound terrier and a 100-pound Great Dane can be substantial. Food choices also matter.
Some owners purchase standard dry food, while others prefer premium kibble, wet food, fresh-food subscriptions, or veterinary prescription diets. There can be meaningful price differences between those options.
For perspective, a household spending $70 a month on dog food pays $840 annually. Increasing that budget to $150 a month raises the annual expense to $1,800. That’s another $960 per year, without changing anything else about the dog’s care.
You shouldn’t automatically assume that the most expensive food is the best choice. The more useful question is whether a diet is nutritionally appropriate for the dog’s age, size, health, and activity level.
A veterinarian can help determine that. Treats are another expense worth tracking separately. Rover estimates annual spending of $55 to $360 on treats and chews.
A few small purchases each week can easily turn into a few hundred dollars over a year.
Veterinary Care Is More Than an Annual Checkup
Rover lists annual veterinary visits for adult dogs at approximately $80 to $135. However, that figure shouldn’t be mistaken for a complete annual medical budget. An examination is only one possible expense.
Vaccinations, diagnostic tests, dental procedures, medications, and treatment for health conditions may create additional charges.
The American Animal Hospital Association’s preventive care guidance emphasizes regular examinations, vaccinations, parasite prevention, and individualized healthcare plans. The appropriate schedule depends on the dog.
A healthy young adult may need relatively little medical attention beyond routine preventative care. Another dog could require ongoing treatment for allergies, digestive problems, joint conditions, or other illnesses.
These differences matter financially because medical expenses are not always optional or easily postponed.
Rover also estimates annual flea, tick, and other preventative medication expenses at $295 to $360. That’s roughly $25 to $30 a month.
Dental hygiene adds another estimated $55 to $490 a year. Professional dental procedures, particularly those requiring anesthesia or additional treatment, may cost more than basic at-home dental care.
My concern with extremely tight pet budgets is that owners sometimes treat veterinary care as money they’ll spend only when something goes wrong.
That approach makes the budget look cheaper, but it doesn’t eliminate the dog’s healthcare needs.
Pet Insurance Adds $520 to $1,230 Annually
Pet insurance is another significant expense. Rover estimates that insuring an adult dog can cost approximately $520 to $1,230 per year, or $43 to $103 each month.
Whether that expense makes financial sense depends on the policy, the dog, and the owner’s ability to cover unexpected veterinary bills. Insurance doesn’t necessarily make routine pet ownership cheaper.
Instead, its main purpose is to help manage certain large, eligible medical expenses that might otherwise create financial difficulties.
Policies vary in several important ways:
- Deductibles: How much the owner must pay before eligible reimbursement begins.
- Reimbursement rates: The percentage of covered expenses an insurer will repay.
- Annual limits: The maximum amount an insurer will reimburse during a policy year.
- Exclusions: Conditions or treatments the policy won’t cover.
- Waiting periods: How long coverage takes to become effective for certain conditions.
Most accident-and-illness policies don’t automatically cover routine wellness visits, vaccinations, and preventative care.
Pre-existing conditions are also commonly excluded. That distinction is rather important.
A $700 annual insurance policy doesn’t mean the owner will avoid spending money at the veterinarian. Premiums, deductibles, excluded services, and the owner’s share of covered bills can all remain part of the household budget.
For someone who could comfortably handle a several-thousand-dollar emergency, setting aside money independently may be an option.
For someone who couldn’t, insurance may provide valuable protection against certain large bills. Neither approach eliminates financial risk.
The Size of Your Dog Makes a Major Difference
One of Rover’s more revealing findings is that small-breed adult dogs can cost as much as 63% less annually than large- or giant-breed adults.
That’s a substantial difference for households considering which type of dog they can afford. Food is the most obvious reason. A larger dog needs more of it. But size affects other expenses as well.
Medication prices can depend on weight. Larger dogs often require bigger beds, crates, collars, and harnesses.
Professional grooming may take longer and cost more. Some veterinary procedures can also be more expensive for larger animals. Breed characteristics matter independently of size.
A small dog requiring regular professional grooming could cost considerably more to maintain than a similarly sized short-haired dog.
Likewise, dogs with inherited health concerns may require additional medical monitoring or treatment.
Prospective owners should pay at least as much attention to a breed’s typical maintenance requirements as they do to its appearance.
A dog that costs relatively little to adopt can still be expensive to care for over the next decade.
Grooming, Boarding, and Other Expenses Can Push Costs Higher
The annual ownership estimate is useful, but it doesn’t capture every possible household expense.
Some dogs require services that other owners rarely purchase. Consider professional grooming.
Rover estimates that owners of dogs with high-maintenance coats may spend approximately $300 to $975 annually on professional grooming.
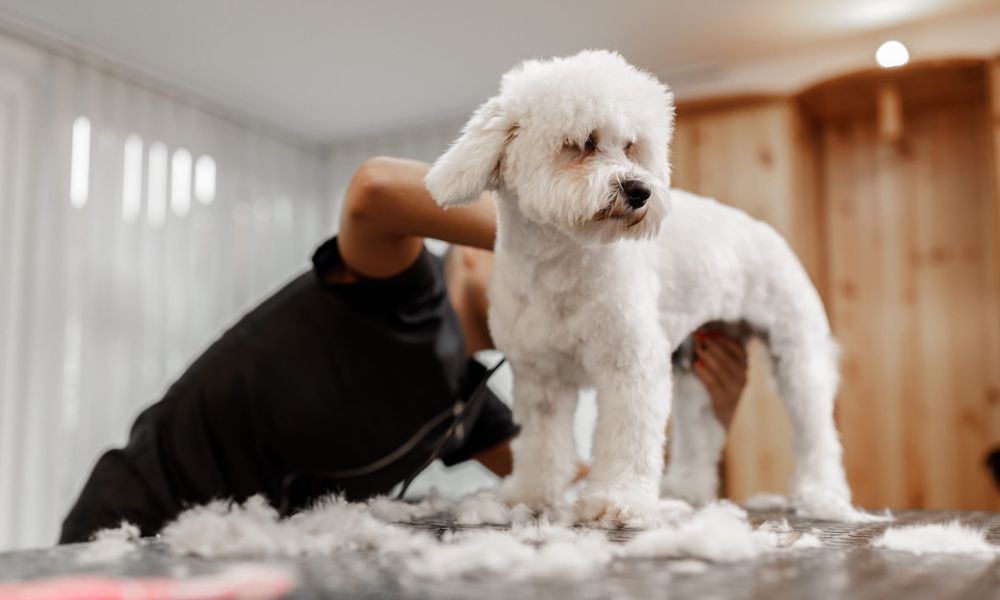
For certain breeds, regular grooming is part of maintaining a healthy, manageable coat rather than simply a cosmetic preference.
Boarding, dog walking, and daycare can also become substantial expenses. An owner working from home might rarely need paid walking services.
Someone who regularly travels or works long hours away from home could depend on them several times a week. Housing introduces another potential cost.
Renters may encounter pet deposits, monthly pet rent, or restrictions that influence which apartments they can afford. Moving with a dog may also narrow the available housing options.
Then there are the smaller discretionary purchases.
Extra toys, clothing, accessories, seasonal products, and specialty treats can all increase annual spending.
We explored one example in an earlier article about Americans spending $920 million on pet costumes. A Halloween costume is hardly a financial crisis by itself.
However, it illustrates how pet spending can extend beyond the necessities into an entirely separate lifestyle budget.
The financial difference is that costumes and accessories are generally optional. Food, appropriate medical care, and essential supplies aren’t.
Emergency Veterinary Bills Are the Biggest Financial Wild Card
The most important number in a dog owner’s budget may be the amount available for an unexpected medical emergency.
Rover estimates that emergency veterinary expenses can range from $300 to $2,500 in its additional-expenses breakdown.
It also notes that some emergency visits can reach $4,000, depending on the treatment and whether overnight care is needed.
More complicated cases can cost even more. Now consider what happens to a household that normally spends $2,500 a year caring for its dog.
A $2,000 emergency could bring that year’s spending to $4,500, assuming the emergency is an additional out-of-pocket expense.
That is an 80% increase over the original budget. It’s also why you shouldn’t use the $5,305 upper estimate as a maximum possible annual cost.
Keep in mind that the annual range is a planning benchmark, not a ceiling on what a dog might cost.
Rover’s 2026 survey found that 38% of pet parents couldn’t cover an emergency veterinary visit without taking on debt. Only 10% reported starting or contributing to a savings account specifically for pet expenses or emergencies.
Those findings suggest that many households are financially exposed to costs they know could eventually occur.
A separate 2025 study from Synchrony found that 74% of pet owners had experienced unexpected pet care expenses exceeding $250.
The research also found that nearly eight in ten owners underestimated the lifetime cost of caring for a pet.
That’s the central budgeting problem. People generally understand that pets cost money.
What’s harder is anticipating how those expenses accumulate, particularly when several unusual bills arrive close together.
The First Year With a Dog Can Cost More
If you’re planning to adopt or purchase a dog, annual maintenance expenses are only part of the calculation. Rover estimates the upfront cost of bringing a dog home in 2026 at $1,195 to $4,650.
That includes a range of initial expenses, depending on the animal and circumstances.
Examples from Rover’s research include:
| Initial Expense | Estimated Cost |
|---|---|
| Adoption fee | 50–500 |
| Purchasing from a breeder | 675–4,440 |
| Spaying or neutering | 300–800 |
| Initial veterinary examination | 80–180 |
| Vaccinations | 180–300 |
| Essential supplies | 260–1,125 |
| Microchip and identification | 30–80 |
An adult dog adopted from a shelter may already be vaccinated, microchipped, and spayed or neutered.
That can reduce initial expenses significantly. A puppy purchased from a breeder may require more veterinary appointments and additional supplies.
Rover estimates annual puppy care expenses at $1,460 to $6,745, compared with $1,930 to $5,305 for adult dogs.
Those life-stage ranges reflect different needs and spending patterns. They shouldn’t be interpreted as proof that every puppy costs less or more than every adult dog.
Also, upfront and annual expense categories can overlap. Simply adding the two headline ranges together may double-count some purchases.
The approach is to identify exactly which services and supplies are already included when bringing the dog home.
How Much Does a Dog Cost Over Its Lifetime?
Annual ownership costs become much more meaningful when viewed over an animal’s entire life.
Rover’s 2026 research estimates the median lifetime cost of a medium-sized dog at approximately $39,350.
Its breed-size estimates extend from about $19,840 for a small dog to $58,875 for a large dog.
Veterinary Secrets also highlights how routine pet care and unexpected veterinary bills can add up over time. The following video offers another perspective on the long-term financial commitment of pet ownership.
Those are considerable long-term financial commitments.
And they help explain why the first year of ownership doesn’t necessarily provide an accurate picture of everything that follows.
A dog may need relatively little medical treatment for several years, then develop conditions requiring additional care as it ages.
Food needs can change. Insurance premiums can rise. Grooming and medication requirements may change as well. Rover estimates annual senior-dog expenses at $2,475 to $5,200, excluding end-of-life care.
It’s important not to interpret that upper figure as a limit on senior-dog spending, especially since certain older dogs can face substantial medical expenses.
From a household finance perspective, dog ownership resembles other long-term commitments with both predictable and unpredictable costs.
You can estimate what you’ll spend in a normal month. You can’t know exactly what every future year will bring.
How You Should Build a Realistic Dog Ownership Budget
For a household preparing to adopt an adult dog, begin with a monthly budget rather than relying exclusively on an annual estimate.
That makes it easier to see whether the cost fits alongside rent, groceries, transportation, debt payments, and other obligations.
Here is one possible approach.
Example: A $3,000 annual dog-care budget
| Budget Component | Monthly Allocation |
|---|---|
| Food and treats | $95 |
| Routine veterinary care and preventatives | $50 |
| Pet insurance | $65 |
| Grooming, toys, and supplies | $25 |
| Training and miscellaneous expenses | $15 |
| Total | $250 |
It assumes a dog whose needs can be met within these amounts. Costs for vaccinations, dental procedures, specialized diets, and other services could require adjustments.
The advantage of a monthly approach is that it spreads irregular expenses across the year. An annual veterinary appointment doesn’t need to become a financial surprise if money has been reserved for it every month.
However, consider creating a separate emergency savings category. For example, setting aside another $50 monthly would build $600 in emergency savings over a year.
That would increase the household’s monthly cash allocation from $250 to $300, although the $50 savings contribution isn’t itself a pet-care expense until the money is used.
And $600 wouldn’t necessarily cover a major emergency. It’s a starting point toward a larger reserve, not a substitute for evaluating potential medical costs.
If you choose to carry pet insurance, the emergency fund can still help cover deductibles, noncovered services, and expenses awaiting reimbursement.
Where Dog Owners Can Save Money Without Sacrificing Care
Not every pet-related expense is equally difficult to control.
There are several opportunities to manage spending without automatically choosing the cheapest available product or service.
- Compare food costs by quantity and feeding requirements. A large bag may offer a better price per pound, but the cheapest price per pound isn’t necessarily the lowest cost per day of feeding. Nutritional suitability should come first.
- Ask for veterinary estimates. For nonemergency procedures, an itemized estimate can help owners understand which services are necessary and what alternatives may be available.
- Consider preventative care. Routine appointments, parasite prevention, and appropriate dental care have value beyond their immediate cost. Skipping recommended care purely to save money may create health risks and potentially larger bills.
- Review insurance annually. Premiums, coverage limits, deductibles, and exclusions matter. Comparing policies can be useful, but switching insurers may affect coverage for conditions that have already developed.
- Handle suitable grooming tasks at home. Regular brushing and basic coat maintenance may reduce professional grooming expenses for some dogs. More complicated grooming needs may still require a professional.
- Be selective about accessories. Dogs need safe, functional supplies. They don’t necessarily need frequent upgrades to beds, bowls, clothing, or toys.
What the $1,930 to $5,305 Estimate Really Tells Us
Rover’s research offers a useful picture of what it can cost to care for an adult dog in 2026. At the low end, $1,930 annually may be manageable for many households.
At the high end, $5,305 represents more than $440 a month before considering any unusually expensive emergency or major additional service.
And with Rover estimating the median lifetime cost of a medium-sized dog at $39,350, this is clearly a long-term financial decision.
We don’t think these figures should discourage people from owning dogs. They should encourage people to understand the commitment before making it.
The adoption fee may be a one-time expense, but food, veterinary care, prevention, and other essentials continue for years.
The biggest takeaway is that the best dog budget isn’t necessarily the cheapest one. It’s the one that realistically covers the dog’s needs and leaves the household prepared for something unexpected.
That’s what makes responsible pet ownership financially sustainable.